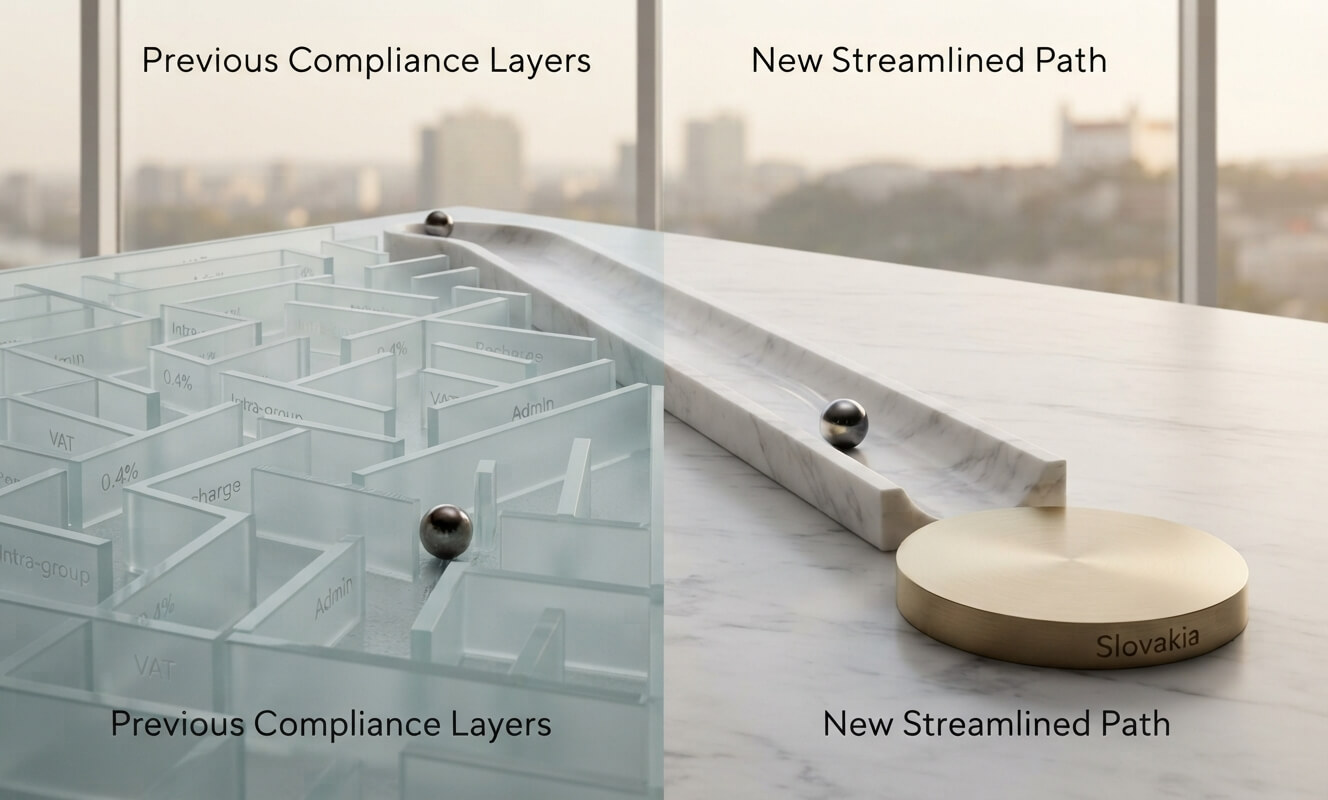
The Slovak government has initiated a significant policy reversal, directing the Finance Ministry to draft legislation to scrap the country’s disputed financial transaction tax. Originally established as part of a wider fiscal consolidation framework, the levy applied a 0.4 percent charge on standard business debit transfers, creating substantial compliance friction for commercial entities, holding structures, and international groups operating through Slovak branches or permanent establishments.
Following sustained feedback from business federations, corporate groups, and foreign investors who cautioned that the levy impaired national competitiveness within the eurozone, the pending repeal marks an important pivot in Slovakia’s economic environment. For cross-border corporate groups and regional holding entities, this development requires a prompt review of treasury routing, liquidity management, and operational setups.
Background and Structural Impact of the Levy
During its implementation, the financial transaction tax specifically targeted corporate accounts and legal entities, applying charges not only to direct debit transfers but also capturing intricate intra-group cash flows, recharged expenses, and payments executed across foreign accounts linked to local permanent establishments.
Unlike standard corporate income taxes calculated on net profits, the transaction levy operated as a direct friction on capital movement, disproportionately affecting transaction-heavy sectors, supply-chain intermediaries, and centralized treasury management models such as cash pooling. Multinational enterprises with Slovak subsidiaries previously had to reorganize intra-group financing and cost-allocation frameworks to mitigate exposure to the charge, increasing administrative overhead and complicating local corporate structuring.
Strategic Realignments for Corporate Groups
Although the upcoming removal of the tax eliminates a major operational hurdle for corporate liquidity, international groups and regional investors must integrate the transition into their broader tax and operational planning:
- Treasury and Cash Pooling Restructuring: Corporate treasurers who previously adjusted cash-sweeping schedules or established specialized accounts solely to isolate transaction-tax exposure can dismantle these defensive frameworks, restoring streamlined liquidity management across regional operating entities.
- Recharged Expenses and Cost-Allocation Reviews: With the transaction-based levy scheduled for removal, inbound and outbound service fees, management charges, and cost-reallocation mechanisms between foreign parent entities and Slovak subsidiaries return to standard corporate income tax and withholding tax oversight without an underlying transactional penalty layer.
- Entity and Branch Validation: Foreign enterprises that delayed setting up localized subsidiaries or considered altering permanent establishment footprints due to transaction-tax liabilities can reassess clean, direct corporate entry options within the Slovak market.
Navigating Ongoing Compliance and Capital Strategy
As Slovakia prepares to dismantle the transaction tax framework, corporate groups must audit their existing banking setups, intercompany agreements, and cash-flow routing to ensure complete alignment with the incoming regulatory baseline.
Explore our International Tax Advisory Capabilities or reach out directly to our advisory team:
JUDr., LL.B, LL.M
Founder of Benson Formations and Vasil Group – specialist in cross-border Tax & Business Structuring.
Email: office@bensonformations.com
Phone: +44 203 974 1244
Benson Formations 25+ years, 60+ Jurisdictions, a boutique consultancy, company formation and corporate services firm focused on helping modern entrepreneurs set up and run their onshore and offshore companies. Benson Formations is the corporate services branch of Vasil Group, which delivers legal, accounting, advisory and corporate services.